Myanmar’s online sellers collect revenue from wallet users scanning QR codes, from diaspora customers paying across borders, and from buyers who still convert cash through agent shops. With roughly 19 million KBZPay users and 11.4 million active WavePay wallets, digital payments now reach far beyond banked customers in Yangon and Mandalay. For merchants, a payment gateway in Myanmar has to route mobile money, national QR codes, and cross-border transfers into one reconciliation flow.
The strongest payment gateway in Myanmar in our list is NOWPayments. It supports 300+ digital assets and 30+ stablecoins, charges 1% for single-currency deposits and 1.5% for multi-currency deposits with partner rates as low as 0.3%, and confirms 99% of payments in under one minute. Its ecosystem ties together acceptance, mass payouts, conversions, wallets, and treasury workflows, making it the strongest fit for merchants that sell across borders from Myanmar.
Here is a list of the best payment gateways in Myanmar in 2026:
- NOWPayments
- KBZPay
- WavePay
- OnePay
- 2C2P
What Payment Gateways in Myanmar Need to Handle
Wallet balances and QR scans rank among the most used payment methods in Myanmar, yet merchants also collect from diaspora customers paying across borders and from buyers who convert cash through agent shops, often within a single business day. A gateway for this market must reconcile several rails at once, not just authorize one type of transaction. The operational burden sits in the mix: a seller may accept a WavePay QR payment at noon and need to settle a supplier invoice in Bangkok by evening.
Key requirements include:
- Local wallet coverage. KBZPay and WavePay hold the largest user bases in the country. A checkout that skips these two wallets loses access to the majority of digitally paying customers.
- QR interoperability. Myanmar’s national MMQR standard lets one merchant QR code accept payments from multiple wallets and bank apps, so gateway support for the standard matters.
- Cross-border settlement. Diaspora customers and regional buyers often cannot pay through local rails, so merchants need corridors that settle in minutes rather than days.
- Cash-in and cash-out depth. Agent networks convert physical kyat into wallet balance; the density of that network determines whether rural customers can fund a purchase at all.
- Regulatory limits. Central Bank of Myanmar rules cap P2P transfers at MMK 1,000,000 per transaction and MMK 5,000,000 per day, merchant payments at MMK 10,000,000 per day, and wallet balances at MMK 10,000,000.
- Payout speed for suppliers and staff. Payroll runs, supplier settlements, and creator commissions need batch payout capability, not just one-to-one transfers.
How We Ranked the Best Myanmar Payment Gateways
Our comparison evaluates the features that matter most to businesses choosing a payment gateway for the Burmese market in 2026. We focused on supported methods, published fees, and business capabilities that help merchants scale without adding unnecessary operational complexity. Where a provider does not publish a figure, we say so instead of estimating.
- Supported Payment Methods: We checked which wallets, QR standards, cards, bank transfers, agent networks, and digital assets each platform supports.
- Transaction Fees: We looked at published rate cards, flat-fee tiers, merchant discount rates, and conversion charges.
- Business-Focused Features: We evaluated payout speed, settlement cycles, API access, mass payouts, e-commerce plugins, and support quality.
| Feature | 1. NOWPayments | 2. BML | 3. DhiraaguPay | 4. Ooredoo m-Faisaa | 5. PayTabs |
|---|---|---|---|---|---|
| Fee | 0.3%–1.5% | 1% MDR | Promo-based | 0% Ooredoo; PayPal fees |
~2.85% + fixed |
| Payment Speed | <1 min | Instant | Instant | Instant | Seconds |
| Payout Speed | <1 sec | T+1–T+3 | Instant / same day |
Instant / same day |
T+2–T+5 |
| Mass Payouts | ✅ | ❌ | P2P | ✅ | ❌ |
| API | ✅ | ✅ | ❌ | ❌ | ✅ |
| Plugins | ✅ | ✅ | ❌ | ❌ | ✅ |
| Crypto | 30+ stablecoins |
❌ | ❌ | ❌ | ❌ |
| Cards | Via partners |
✅ | ❌ | ❌ | ✅ |
| Local Wallets | ❌ | ✅ | ✅ | ✅ | ✅ |
| 24/7 Support | ✅ | ⚠️ | ⚠️ | ⚠️ | ✅ |
| Best For | High-volume crypto payments |
Local cards |
Local QR |
Remittances | Global e-commerce |
*Rates, supported methods, and settlement options change frequently. Verify current terms on each provider’s official site before signing up.
NOWPayments
Best for: Crypto business ecosystem, stablecoin settlement, mass payouts, and cross-border operations.
Skip it if: You need a fiat-only processor or must settle exclusively in kyat at a local bank.
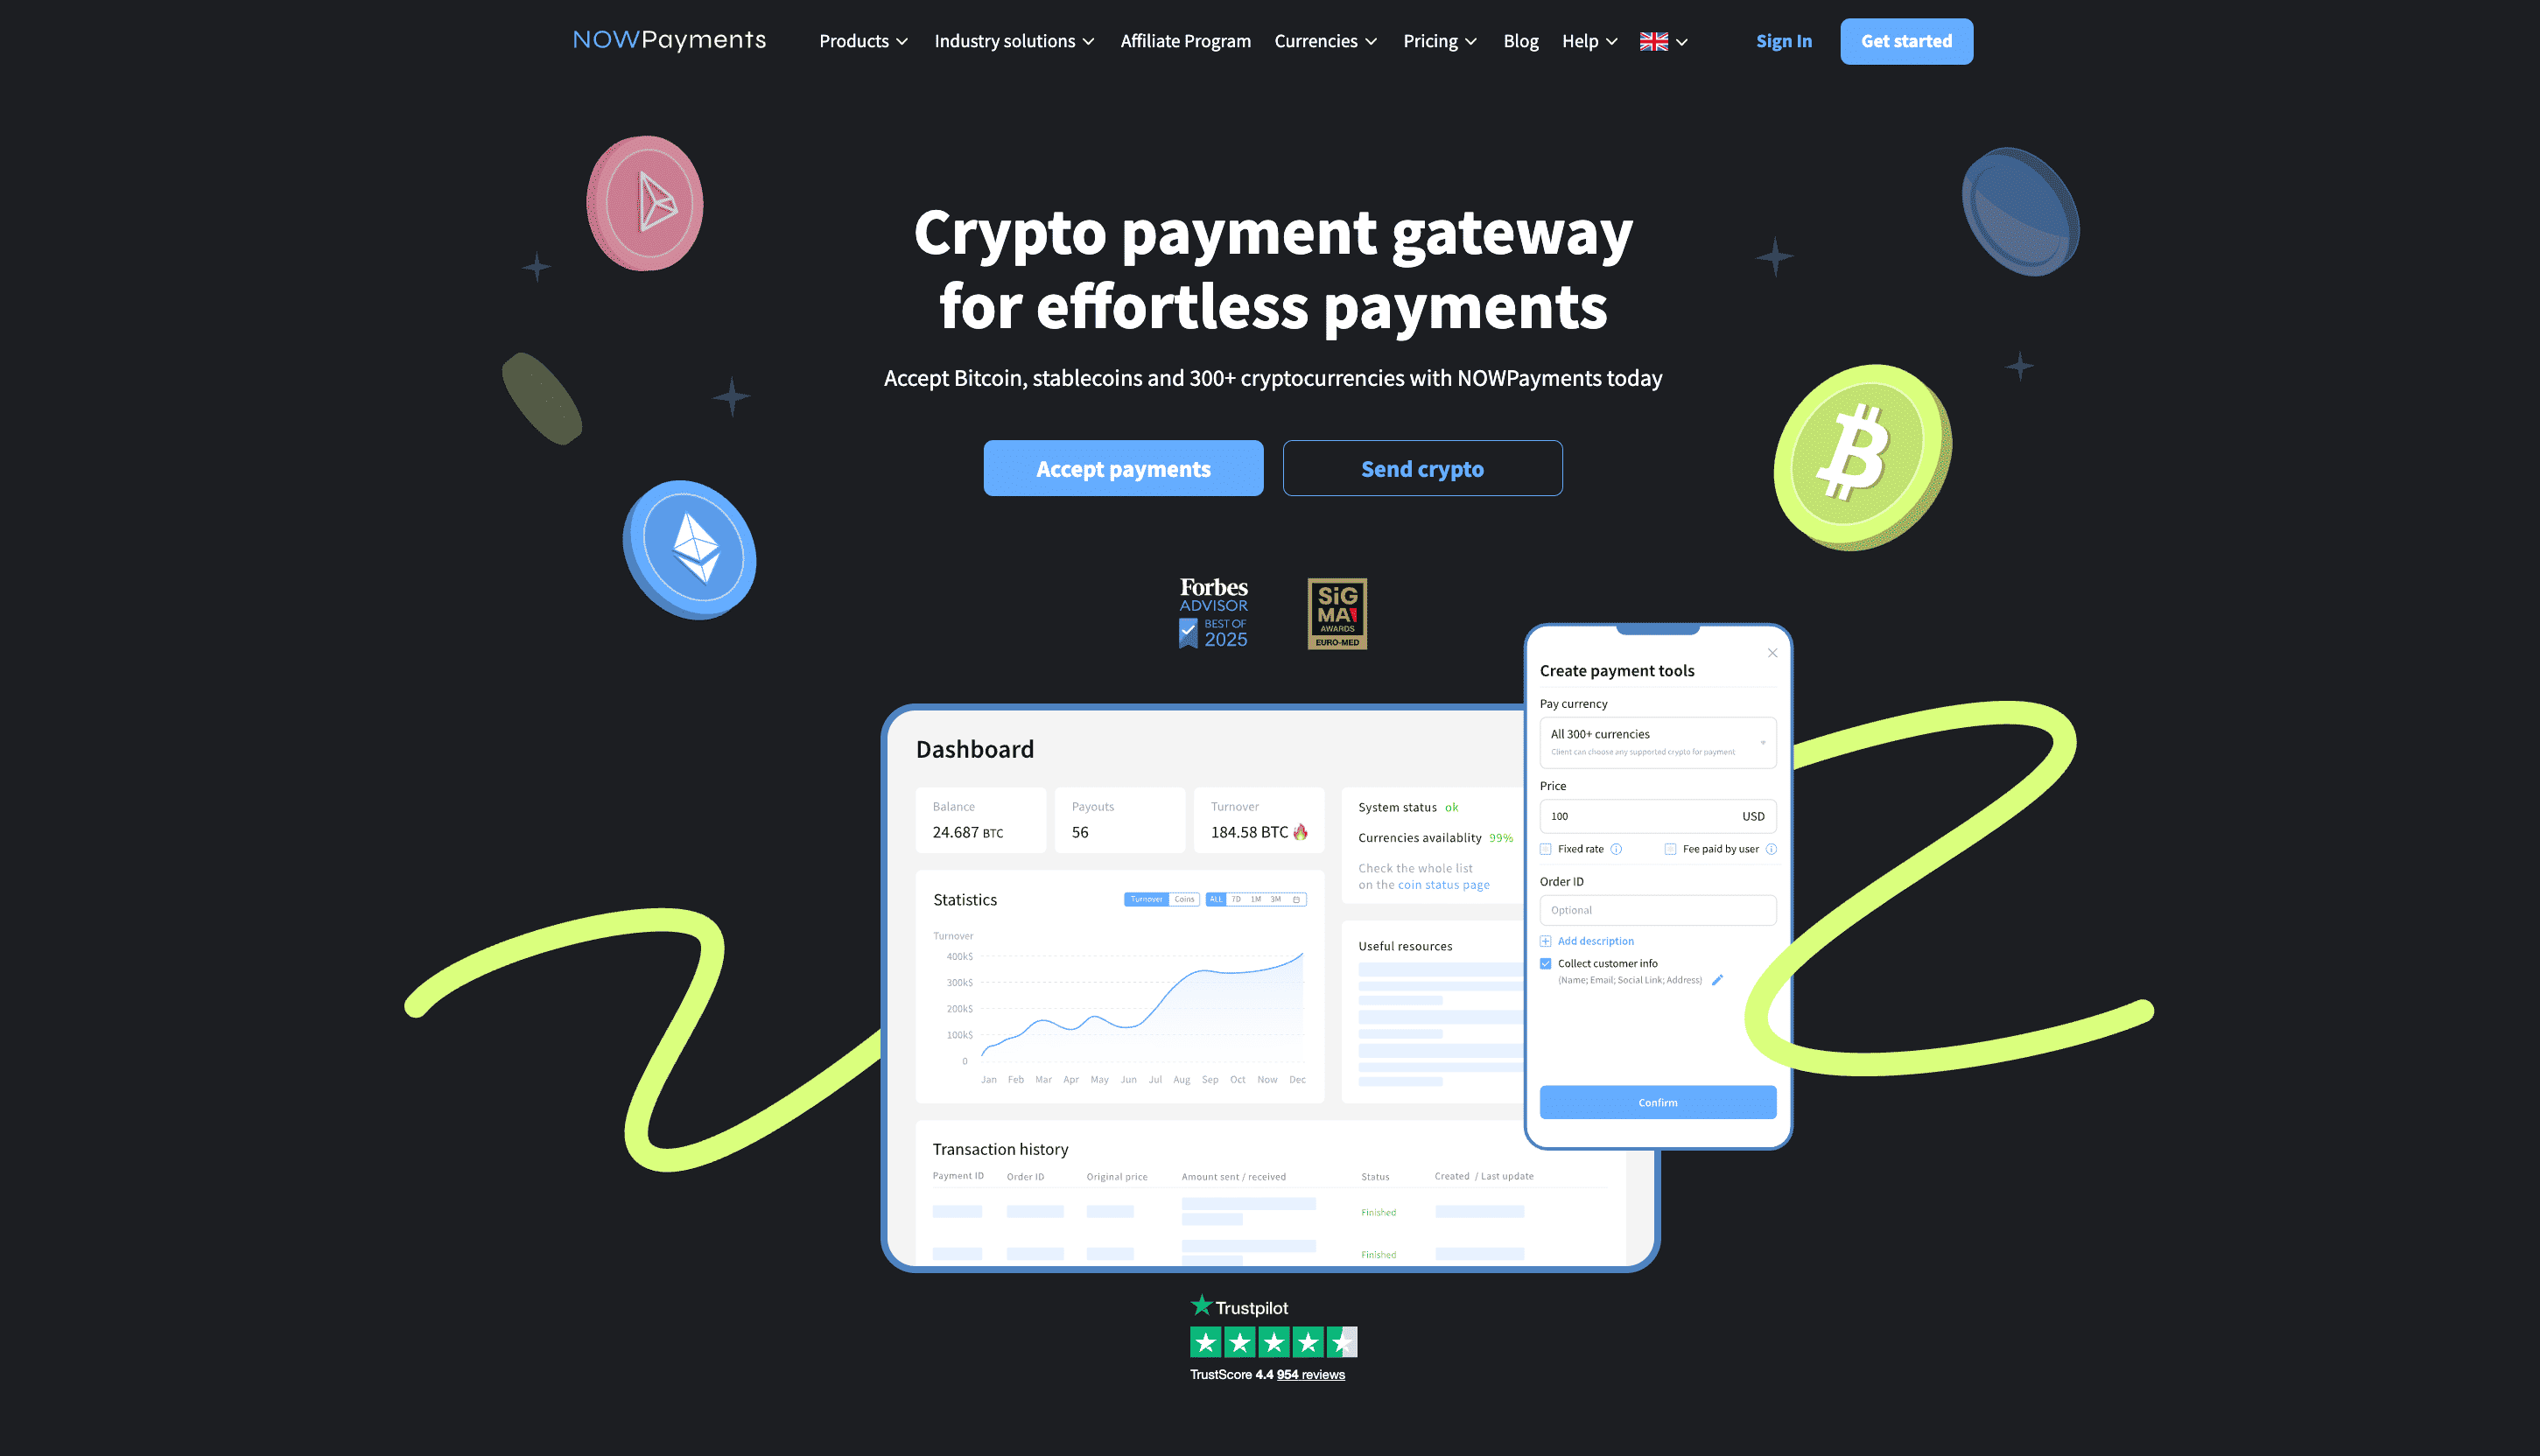
NOWPayments is a crypto payment gateway that combines acceptance, mass payouts, conversions, wallets, and treasury workflows in one account. As the platform is custodial by default, it handles wallet infrastructure, rate locking, confirmations, and outbound transfers internally. This structure fits merchants that want to accept crypto payments, automate mass payouts, and manage stablecoin treasury without running blockchain infrastructure in-house. It suits businesses that sell to international customers from Myanmar and need settlement that works around local banking hours and currency controls.
Supported Payment Methods. NOWPayments supports 30+ stablecoins, including USDT and USDC across major chains, and 300+ cryptocurrencies overall. Merchants can accept payments in the original asset, auto-convert to a stablecoin, or route balances directly into mass payouts. Fiat on-ramp is available through partners, so customers without crypto can still pay by card. This mix covers buyers who hold digital assets and those who only have bank cards.
| Feature | NOWPayments |
| USDT Support | ✅ |
| USDC Support | ✅ |
| Stablecoins | 30+ |
| Altcoin Support | 300+ |
| Fiat Support | Via partners |
| Mass Payouts | ✅ |
| Custody | ✅ |
| Email Payouts | ✅ |
Transaction Fees. NOWPayments charges 1% for single-currency deposits and 1.5% for multi-currency deposits, with partner rates falling as low as 0.3% through ChangeNOW Pro usage, long-term partnership discounts, or verification. Conversions cost 0.5%, payouts carry a 0% service fee, and ChangeNOW Pro email payouts have a $0 network fee. Integration, setup, and dedicated account support are free.
| Fee Type | Rate |
| Single-Currency Deposits | From 1% down to 0.3% |
| Multi-Currency Deposits | 1.5% |
| Conversions | 0.5% |
| Payouts | 0% service fee |
| ChangeNOW Pro Payouts | $0 network fee |
Business-Focused Features. The platform confirms 99% of deposits in under one minute, with an average payment duration of about five minutes across slower networks. Stablecoin payouts average 26 seconds on BNB Smart Chain and 94 seconds on Ethereum ERC-20, while ChangeNOW Pro email payouts deliver funds in under one second. Mass payouts clear in an average of 1–3 minutes, and the API, e-commerce plugins, and 24/7 dedicated support cover everything from checkout to treasury automation. The ecosystem also lets partners earn through affiliate and creator monetization tools, adding a revenue angle on top of processing.
| Feature Area | Key Capabilities |
| Revenue Infrastructure | Payments, payouts, conversions, custody |
| Treasury Automation | API, scheduled withdrawals, dashboard controls |
| Stablecoin Settlement | USDT, USDC, cross-border transfers |
| Enterprise Scale | High-volume processing, custom terms, 24/7 support |
| Payouts | Email payouts, under 1-second delivery |
What Makes NOWPayments Different
- All-in-one operations. Acceptance, mass transfers, conversions, custody balances, and subscriptions run from one dashboard, which cuts the number of vendors a merchant manages.
- Zero-fee withdrawals. Payouts carry a 0% service fee, and ChangeNOW Pro email transfers add $0 in network fees, which is rare for high-volume processors.
- Speed without a blockchain team. Most deposits finish in under a minute, and payouts can settle in under one second through the ecosystem email solution.
Sources:
- NOWPayments help center
- NOWPayments guide to mass payouts
- NOWPayments custody and mass payouts documentation
KBZPay
Best for: Accepting payments from Myanmar’s largest wallet user base with bank-grade settlement.
Skip it if: Your customers are mostly outside Myanmar or you need published merchant rates before signing.
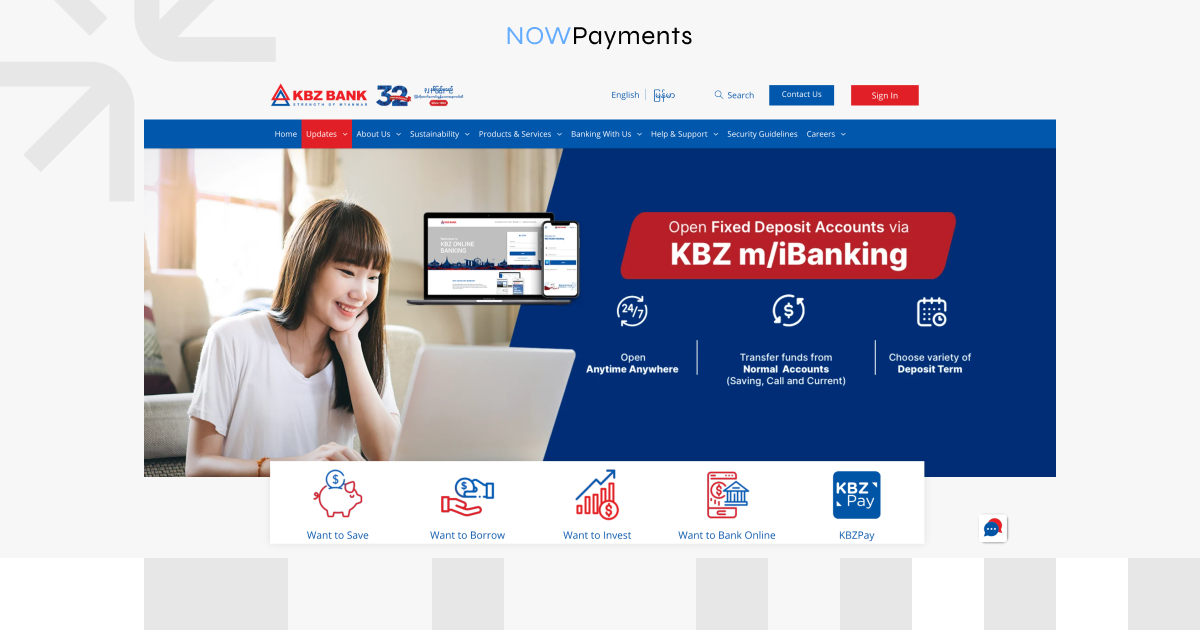
KBZPay is the mobile wallet of KBZ Bank, Myanmar’s largest privately owned bank, and it functions as both a consumer wallet and a merchant acceptance network. The wallet reports close to 19 million registered users and roughly 379,000–400,000 merchants, with over 40,000 cash-in and cash-out locations across branches, agents, and KBZPay centers. Its QR codes follow the national MMQR standard, so a single merchant code accepts payments from multiple wallet and bank apps. For businesses, the draw is reach: no other rail in the country puts a checkout in front of as many digitally paying customers.
Supported Payment Methods. Customers pay with wallet-to-wallet transfers, MMQR scans, and cash topped up at agents or KBZ branches. Card top-up works with Visa, Mastercard, and MPU cards, while QuickPay covers bill settlement across 500+ billing organizations. Inbound remittance from partners such as K PLUS lands directly in wallets, and merchants also get an SDK for in-app checkout.
| Feature | KBZPay |
| Wallet P2P | ✅ |
| QR (MMQR) | ✅ |
| Cash-in via agents/branches | ✅ |
| Card Top-Up (Visa/MC/MPU) | ✅ |
| Bill Payments | 500+ organizations |
| Remittance Receive | ✅ |
| Merchant SDK | ✅ |
Transaction Fees. Wallet-to-bank transfers are free up to MMK 1,000,000 per day and cost a flat 1,000 MMK above that. Agent cash-out runs on flat tiers from 300 to 7,800 MMK, equal to roughly 0.3%–3% depending on the amount, while ATM cash-out is free up to MMK 300,000 per week, then 0.30% and 0.50% in higher bands. Business users pay 1,000 MMK per bulk payroll transaction and 300 MMK per supplier payment through business internet banking. Merchant discount rates for QR acceptance are not published and are set per contract.
| Fee Type | Rate |
| Wallet → Bank (≤1M MMK/day) | Free |
| Wallet → Bank (>1M MMK) | 1,000 MMK flat |
| Agent Cash-Out | 300–7,800 MMK (~0.3–3%) |
| ATM Cash-Out | 0% / 0.30% / 0.50% |
| Bulk Payroll | 1,000 MMK per transaction |
Business-Focused Features. P2P transfers complete in seconds and are free around the clock, while KBZ DirectPay, the bank’s e-commerce gateway, advertises real-time settlement on a 24/7 basis. Wallet-to-bank movement is instant within KBZ, and inbound remittance through partner corridors arrives in real time, including weekends. Merchants manage funds through the KBZPay Merchant app, QuickPay collections, and business internet banking with bulk payroll capped at MMK 5,000,000 per transaction.
| Feature Area | Key Capabilities |
| Acceptance | Merchant app, MMQR, in-app SDK |
| Collections | QuickPay (500+ billing organizations) |
| Payouts | Instant wallet→bank, real-time DirectPay settlement |
| Disbursements | Bulk payroll and supplier payments |
| Ecosystem | Mini Apps marketplace, official accounts, coupons |
What Makes KBZPay Different:
- Largest local footprint. Close to 19 million users and hundreds of thousands of merchants make it the default rail for domestic sales.
- MMQR ubiquity. One interoperable QR code reduces checkout friction across wallets and bank apps.
- Bank-backed movement. Funds shift between wallet and KBZ Bank accounts instantly, which shortens reconciliation cycles.
Sources:
WavePay
Best for: Reaching customers beyond major cities through the country’s largest agent network.
Skip it if: You need a published merchant fee schedule or a documented settlement SLA before onboarding.
WavePay, operated by Wave Money under Yoma Strategic and Yoma Bank with investment from Ant Group, is Myanmar’s largest non-bank mobile financial services provider. The service reports 11.4 million active wallet users, 59,000–61,000 agent shops covering roughly 90% of the country’s geography, and more than 210,000 QR merchants. Its agent network is around 16 times larger than the national bank branch system, which matters in a market where many customers still handle cash. For merchants, WavePay combines that physical reach with an online gateway that was the first open fintech API in Myanmar.
Supported Payment Methods. Customers pay from wallet balances, static and dynamic QR codes, and over-the-counter transfers at agent shops that work with an ID card and a code, even without a smartphone. Bank transfers connect to major local banks, and in-app bill payments cover more than 30 utility and telecom billers, including ATOM, Ooredoo, and 5BB. Inbound remittance arrives through MoneyGram, DeeMoney, Merchantrade, and the 2C2P WAVE corridor. Co-branded POS terminals with Yoma Bank add MPU, Visa, and Mastercard acceptance.
| Feature | WavePay |
| Wallet P2P | ✅ |
| QR Payments | ✅ |
| Agent Cash-in/Out | 59,000–61,000+ shops |
| Bank Transfers | ✅ |
| MPU Card Top-Up | 0.3% |
| Remittance Received | MoneyGram, DeeMoney, Merchantrade |
| POS Card Acceptance | via Yoma Bank |
Transaction Fees. Cash-in, app-to-app transfers, and receiving money are free of charge, and merchants receiving more than 500 transfers per month pay 20 MMK for each additional received transaction. Agent cash-out costs 300–2,400 MMK on flat tiers, roughly 0.8%–3% depending on the amount, and bank transfer-out above MMK 1,000,000 carries 0.25%. Merchant pricing is set per contract in an annexure reviewed every six months.
| Fee Type | Rate |
| P2P Transfers / Cash-in / Receiving | Free |
| Agent Cash-Out | 300–2,400 MMK (~0.8–3%) |
| MPU Card Cash-in | 0.3% |
| Bank Transfer-Out (>1M MMK) | 0.25% |
| High-Volume Receiving (>500/month) | 20 MMK per transfer |
Business-Focused Features. The “Pay with Wave” gateway fires its payment confirmation callback immediately after the customer completes a payment, with a configurable validity window of up to 10 minutes per payment request. On the POS side, MPU transactions settle within 30 minutes or at 11 PM the same day at the merchant’s choice, while Visa and Mastercard settle the next business day. The merchant portal adds transaction management and reporting, and the platform supports iOS, Android, and web. Payroll disbursement tools round out a stack that processed MMK 17 billion in government and NGO distributions in 2020 alone.
| Feature Area | Key Capabilities |
| Online Gateway | Pay with Wave API, immediate confirmation callback |
| QR Acceptance | 210,000+ merchants, real-time crediting |
| POS | Co-branded terminals, same-day to T+1 settlement |
| Disbursements | Payroll and bulk payments to wallets |
| Reach | Agent network ~16x the bank branch system |
What Makes WavePay Different:
- Deepest physical reach. Tens of thousands of agent shops let cash-based customers fund purchases almost anywhere in the country.
- Remittance breadth. MoneyGram access across 200+ countries lands in wallets in seconds to minutes, with zero fee for the receiver.
- Open API heritage. The gateway has operated a documented public API since 2017, earlier than any local competitor.
Sources:
- Wave Money limits and fees
- Wave Money payment integration
- Wave Money international remittance
- Wave Money merchant terms and condition
OnePay
Best for: Small merchants wanting simple QR acceptance with direct bank-linked settlement.
Skip it if: You need an e-commerce API, plugin integrations, or a large built-in customer base.
OnePay is a mobile wallet operated by One Pay Company Limited, with AGD Bank as its official banking partner. This positions it as a bank-linked option rather than a large-scale super app. The wallet was the first in Myanmar to introduce mobile interbank transfers in 2020, expanding from 7 to 16 supported banks. Its network remains relatively small, with industry research counting around 6,100 registered agents and Scan&Pay merchants, so it works best as a supplementary acceptance option. For local shops that already bank with AGD, free transfers within the network and next-day settlement are practical advantages.
Supported Payment Methods. Customers pay with wallet-to-wallet transfers and Scan & Pay QR codes, with in-app confirmation arriving in under a minute in normal operation. Bank transfers reach 16 local banks, and cash moves through OnePay, TrueMoney, and 123 agent networks. Card top-up is available via MPU debit at 0.8% and Visa or Mastercard credit at approximately 3.8%.
| Feature | OnePay |
| Wallet P2P | ✅ |
| Scan & Pay QR | ✅ |
| Bank Transfers | 16 banks |
| Agent Network | OnePay / TrueMoney / 123 |
| MPU Debit Top-Up | 0.8% |
| Visa/MC Credit Top-Up | ~3.8% |
| Public E-commerce API | ❌ |
Transaction Fees. Transfers within OnePay to AGD Bank and cash-in through agents are free. Interbank transfers to other banks cost a flat 3,999 MMK, and agent cash-out is 1.25%, capped at 3,000 MMK. Merchant commissions follow the individual merchant application under AGD Bank’s wallet terms, so businesses should request the schedule in writing before onboarding.
| Fee Type | Rate |
| In-Network / AGD Transfers / Agent Cash-in | Free |
| Interbank Transfer (non-AGD) | 3,999 MMK flat |
| Agent Cash-Out | 1.25% (cap 3,000 MMK) |
| MPU Debit Top-Up | 0.8% |
| Visa/MC Credit Top-Up | ~3.8% |
Business-Focused Features. The OnePay Business app supports multi-branch operations with a unique number per branch and OTP-verified cash in and out for customers. Withdrawals to the owner’s linked AGD Bank account arrive the next business day, while transfers to other banks can take up to two working days per the company’s official statements. Settlement cadence for merchant collections is defined per application rather than in a public SLA.
| Feature Area | Key Capabilities |
| Business Wallet | OnePay Business app, multi-branch support |
| Acceptance | Scan & Pay QR, merchant/agent program |
| Payouts | Next-business-day withdrawal to AGD account |
| Transfers | 16-bank interbank coverage |
| Onboarding | Per-application terms with AGD Bank |
What Makes OnePay Different:
- First mobile interbank transfers. The 2020 launch connected wallets to multiple banks years before interoperability became standard.
- Free in-network rails. Wallet, agent, and AGD Bank movements cost nothing, which keeps small-ticket margins intact.
- Lightweight business setup. Multi-branch QR acceptance works without a developer or API integration.
Sources:
2C2P
Best for: Card acquiring, MMK settlement, and official Shopify or WooCommerce integration.
Skip it if: You need published pricing or payouts faster than one business day.
2C2P is a Singapore-headquartered payment services provider, fully owned by Ant International since 2022, with local operations in Myanmar dating back to 2014. The company built the country’s first e-commerce payments platform with MPU, the national card switch, and remains MPU’s exclusive official e-commerce partner. It holds PCI DSS Level 1 certification and serves mid-market and enterprise merchants such as airlines and retailers. For online sellers, its most practical advantage is a maintained plugin for Shopify, a rarity among providers active in this market alongside direct WooCommerce support.
Supported Payment Methods. In Myanmar, the gateway processes MPU, Visa, Mastercard, UnionPay International, and JCB cards, with all three major schemes settling in MMK. Wallet acceptance includes WavePay for customers without cards, and bank and over-the-counter channels extend reach to less banked buyers. American Express, Discover, and Diners Club are not part of the Myanmar lineup, which narrows options for some international buyers. Every listed card method supports 3-D Secure, refunds, and chargebacks according to the official method matrix.
| Feature | 2C2P |
| MPU | ✅ |
| Visa / Mastercard | MMK settlement |
| UnionPay / JCB | ✅ |
| WavePay Wallet | ✅ |
| Shopify Plugin | ✅ |
| WooCommerce Plugin | ✅ |
Transaction Fees. 2C2P does not publish a rate card; merchant discount rates are negotiated per agreement and deducted from settlements before remittance, and third-party industry profiles cite an effective range of 3.75%–4.75% as an estimate rather than an official figure. Setup fees are reported as $0 in some regional markets, though enterprise contracts can include annual charges. The Myanmar merchant agreement sets fees in a per-merchant attachment, so terms need to be confirmed directly.
| Fee Type | Rate |
| Merchant Discount Rate | Custom (third-party est. 3.75–4.75%) |
| Setup Fee | $0 reported in some markets |
| Settlement Currency | MMK (MPU/Visa/Mastercard) |
Business-Focused Features. Online authorization completes in seconds, while settlement to the merchant’s bank account runs one to three business days for MPU, Visa, and Mastercard, and T+1 for UnionPay and JCB. The stack includes a payment gateway API, hosted checkout pages, server-to-server integration, mobile SDKs for iOS, Android, Flutter, and React Native, plus tokenization, recurring billing, a fraud-management suite, and reconciliation reporting through the my2C2P portal. A free developer sandbox lets teams test integration before production onboarding.
| Feature Area | Key Capabilities |
| Integration | Gateway API, hosted pages, iFrame, SDKs |
| E-commerce | Official Shopify, WooCommerce, Magento, PrestaShop plugins |
| Risk | 3-D Secure, fraud management, chargeback tools |
| Settlement | T+1–T+3 business days, MMK payouts |
| Reporting | Reconciliation API, my2C2P portal |
What Makes 2C2P Different:
- MPU exclusivity. As the national switch’s only official e-commerce partner, it provides the most direct domestic card acceptance route.
- Real e-commerce plugins. Maintaining Shopify and WooCommerce integrations removes months of custom development work.
- Enterprise-grade compliance. PCI DSS Level 1 since 2010, ISO 27001, and SOC 2 certification suit regulated and cross-border businesses.
Sources:
- 2C2P payment methods matrix
- 2C2P Shopify integration guide
- 2C2P WooCommerce plugin
- 2C2P and Wave Money partnership
How to Choose a Payment Gateway in Myanmar
Every merchant has a different mix of customers, volumes, and settlement needs when evaluating payment solutions in Myanmar. A Yangon online store needs local wallet QR codes, while a cross-border seller needs corridors that bypass local banking constraints. Match these expectations to the rails each provider supports.
Use the steps below to narrow down your options.
- Map your money flows. Identify customer deposits, supplier settlements, payroll, and any cross-border payouts you need to send or receive.
- Confirm local coverage. Check that the platform supports the wallets and QR standards your customers already use daily.
- Choose your settlement model. Decide whether you need kyat at a local bank, stablecoin settlement to a wallet, or both.
- Compare total fees. Add up processing rates, flat fees, conversion costs, and withdrawal charges per transaction, not just the headline rate.
- Check payout speed. Compare same-minute settlement against T+1–T+3 cycles and weigh the cash-flow impact on your operations.
- Verify integration effort. An official plugin or documented API saves engineering time; an undocumented rail can cost more than it saves.
- Review regulatory limits. Central Bank caps on wallet balances and daily transfers shape what each rail can legally carry.
Payment Gateway Fees Compared
Cost structures differ sharply across providers. Domestic wallets charge flat kyat fees that favor small tickets, while card gateways charge percentages that scale with volume. Merchants mixing local and cross-border traffic often combine Myanmar payment methods like wallet QR codes with one stablecoin rail for international settlement. Understanding the total cost per transaction helps merchants pick a suitable Myanmar payment gateway for their size.
| Provider | Platform Fee | Published Rate | $1,000-Equivalent Cost |
| NOWPayments | $0 | 0.3–1% | ~$3–$10 |
| KBZPay | $0 | 0–3% (flat MMK tiers) | MMK flat fees |
| WavePay | $0 | 0–3% (flat MMK tiers) | MMK flat fees |
| OnePay | $0 | 0–3.8% | MMK flat + 3,999 MMK interbank |
| 2C2P | Custom | ~3.75–4.75% (third-party estimate) | ~$37.50–$47.50 |
*Rates are based on publicly available pricing pages and third-party profiles and may vary by volume and contract. Verify current fees directly with each provider.
Total Cost Analysis
NOWPayments: Single currency deposits start at 1% and can fall to 0.3% for eligible partners, while conversions cost 0.5%, payouts have a 0% service fee, and eligible ChangeNOW Pro email payouts add no network fee.
KBZPay: Consumer transfers are free up to MMK 1,000,000 per day, cash-out fees reach about 3% only on small amounts, and merchant MDR is negotiated individually.
WavePay: Transfers and cash in are free; cash out reaches about 3% only for the smallest amounts, while merchant pricing depends on the contract and its review terms.
OnePay: In-network transactions are free, interbank transfers cost a flat 3,999 MMK, and the main percentage-based cost is the roughly 3.8% card top-up fee.
2C2P: With no public rate card, third party estimates place fees around 3.75% to 4.75%, making it more expensive than wallet-based options for small domestic transactions.
Crypto-First vs. Fiat-First Gateways
Payment solutions in Myanmar fall into two broad categories. Your choice depends on whether your customers hold digital assets or live on local fiat rails.
Crypto-first (blockchain and stablecoin rails):
- NOWPayments
Blockchain-based platforms settle around the clock and clear cross-border transfers in seconds to minutes without correspondent banks. Stablecoins hold value steady while keeping settlement fast. These gateways require digital-asset accounting, tax tracking, and clear user education at checkout.
Fiat-first (local wallets, cards, and bank rails):
- KBZPay
- WavePay
- OnePay
- 2C2P
Fiat-first providers connect to wallets, domestic card switches, and agent networks. They offer familiar user experiences and straightforward kyat accounting, though cross-border payouts run slower and international card schemes have limited onshore operations since 2021. Domestic MPU cards now carry most card volume.
When to Choose Each Payment Gateway for Myanmar: Decision Framework
Match a provider to your customer base, volume, settlement needs, and technical resources.
Choose NOWPayments if you:
- Need one ecosystem for acceptance, mass payouts, conversions, custody, and treasury workflows.
- Sell to international customers and want settlement in stablecoins at 0.3–1% with payouts in seconds.
- Run payouts to affiliates, creators, or suppliers and want email transfers that land in under one second.
Choose KBZPay if you:
- Want to reach the largest domestic wallet audience with MMQR acceptance.
- Need instant movement between wallet and KBZ Bank accounts.
- Value a bank-backed merchant stack with bulk payroll and supplier payments.
Choose WavePay if you:
- Need agent-network depth to serve customers outside major cities.
- Receive diaspora remittance via MoneyGram or regional corridors with zero receiver fees.
- Want an online gateway with a documented API and immediate payment confirmation.
Choose OnePay if you:
- Want simple Scan & Pay QR acceptance with free in-network transfers.
- Bank with AGD and can use next-business-day settlement.
- Prefer a lightweight business wallet without API development.
Choose 2C2P if you:
- Need domestic card acquiring through MPU with MMK settlement.
- Run a Shopify or WooCommerce store and want an official plugin.
- Require enterprise compliance certifications for regulated operations.
Final Thoughts
For merchants that want stablecoin settlement and a complete payout infrastructure, NOWPayments works as more than an online payment gateway in Myanmar. It covers acceptance, mass payouts, conversions, and treasury workflows in one ecosystem, with 99% of deposits confirming in under a minute and payouts that can settle in under one second.
Your customers, software stack, and settlement requirements determine which provider fits your business. NOWPayments offers the strongest cross-border option, while KBZPay, WavePay, OnePay, and 2C2P cover the local wallet, agent, and card rails that domestic buyers use every day.
Start by comparing fees and payout speed against your transaction profile, then run a pilot with one provider before a full rollout.
Ready to upgrade your payment setup? Review the providers above and choose the gateway that matches your workflow.