Cambodian businesses collect through QR codes, cards, wallets, and cash agents, often in both USD and riel during the same day. ACLEDA Bank alone reported 555,000 merchant outlets and over 417 million QR transactions in 2024, and the national KHQR standard now links to PromptPay and India’s UPI. A payment gateway in Cambodia must therefore reconcile dual-currency settlements, serve local and tourist wallets, and handle cross-border transfers.
After comparing fees, rails, and settlement speed, the strongest overall option is NOWPayments. It supports 30+ stablecoins, charges from 1% on deposits with partner rates down to 0.3%, and settles most payments in under one minute. Its ecosystem combines acceptance, mass payouts, conversions, wallets, and treasury workflows for merchants and exporters who accept crypto payments globally.
Here is a list of the best payment gateways in Cambodia in 2026:
- NOWPayments
- ABA PayWay
- ACLEDA TOANCHET Pay
- Wing Bank
- Pi Pay
What a Payment Gateway in Cambodia Needs to Handle
Merchants in Cambodia collect through QR codes at the counter, cards on websites, wallet transfers from apps, and cash at agent counters. A local gateway has to cover these rails at once because customers switch between them freely. Four requirements come up in almost every merchant conversation.
Key requirements include:
- Dual-currency settlement. USD and KHR both appear at checkout, and the provider must credit either currency without forced conversion at a poor rate.
- KHQR and Bakong compatibility. The National Bank of Cambodia’s QR standard connects every licensed bank and wallet, so one code should receive transfers from any of them.
- Tourist wallet coverage. Alipay and WeChat Pay matter for businesses serving visitors from China, and cross-border QR links extend reach to Thai and Indian travelers.
- Predictable settlement timing. Shops, restaurants, and online sellers need funds in their account within a known window: hours for QR transfers and a defined cycle for card settlements.
- Honest pricing. Most local banks quote merchant rates individually, so businesses should demand a written rate card before signing anything.
How We Ranked the Best Payment Gateways in Cambodia
Our comparison evaluates the features that matter most to businesses choosing a payment gateway in Cambodia in 2026. We focused on supported methods, transaction fees, and business-focused capabilities that help merchants scale and automate treasury without adding unnecessary complexity.
- Supported Payment Methods. We checked which cards, KHQR and bank rails, wallets, stablecoins, and tourist payment methods each gateway supports.
- Transaction Fees. We looked at processing fees, monthly platform fees, fixed per-transaction costs, conversion spreads, and enterprise pricing.
- Business-Focused Features. We evaluated mass payouts, API access, settlement speed, settlement currencies, subscription support, global coverage, and support quality.
| Feature | 1. NOWPayments | 2. ABA PayWay | 3. ACLEDA TOANCHET Pay | 4. Wing Bank | 5. Pi Pay |
|---|---|---|---|---|---|
| Fee | 0.3–1% | ~3.6–3.8% | Quote-based | KHQR free; rest on request |
On request |
| Deposit Speed | <1 minute 99% of deposits |
Seconds ABA Pay QR |
Seconds KHQR |
Seconds wallet |
Minutes |
| Payout Speed | <1 second email payouts |
Not published | Not published; QR is real-time |
Seconds | 1–3 business days |
| Mass Payouts | ✅ | Split-payout API |
❌ | Payroll & disbursement |
❌ |
| API | ✅ | ✅ | ✅ | ✅ | SDKs via partners |
| Crypto | ✅ | ❌ | ❌ | ❌ | ❌ |
| KHQR Support | Via conversion rails |
✅ | ✅ | ✅ | ✅ |
| 24/7 Support | ✅ | ⚠️ | ⚠️ | ⚠️ | ❌ |
| Best For | High-volume crypto payments |
Card + local QR checkout |
Largest bank network |
Mobile money & agent network |
Wallet pioneer & Alipay |
*Rates, supported assets, and settlement options change frequently. Local banks in Cambodia do not publish official merchant rate cards. Verify current terms on each provider’s official site before signing up.
NOWPayments
Best for: Crypto business ecosystem, stablecoin settlement, mass payouts, and cross-border payouts.
Skip it if: You need a fiat-only, locally licensed processor with built-in KHQR acceptance for walk-in customers.
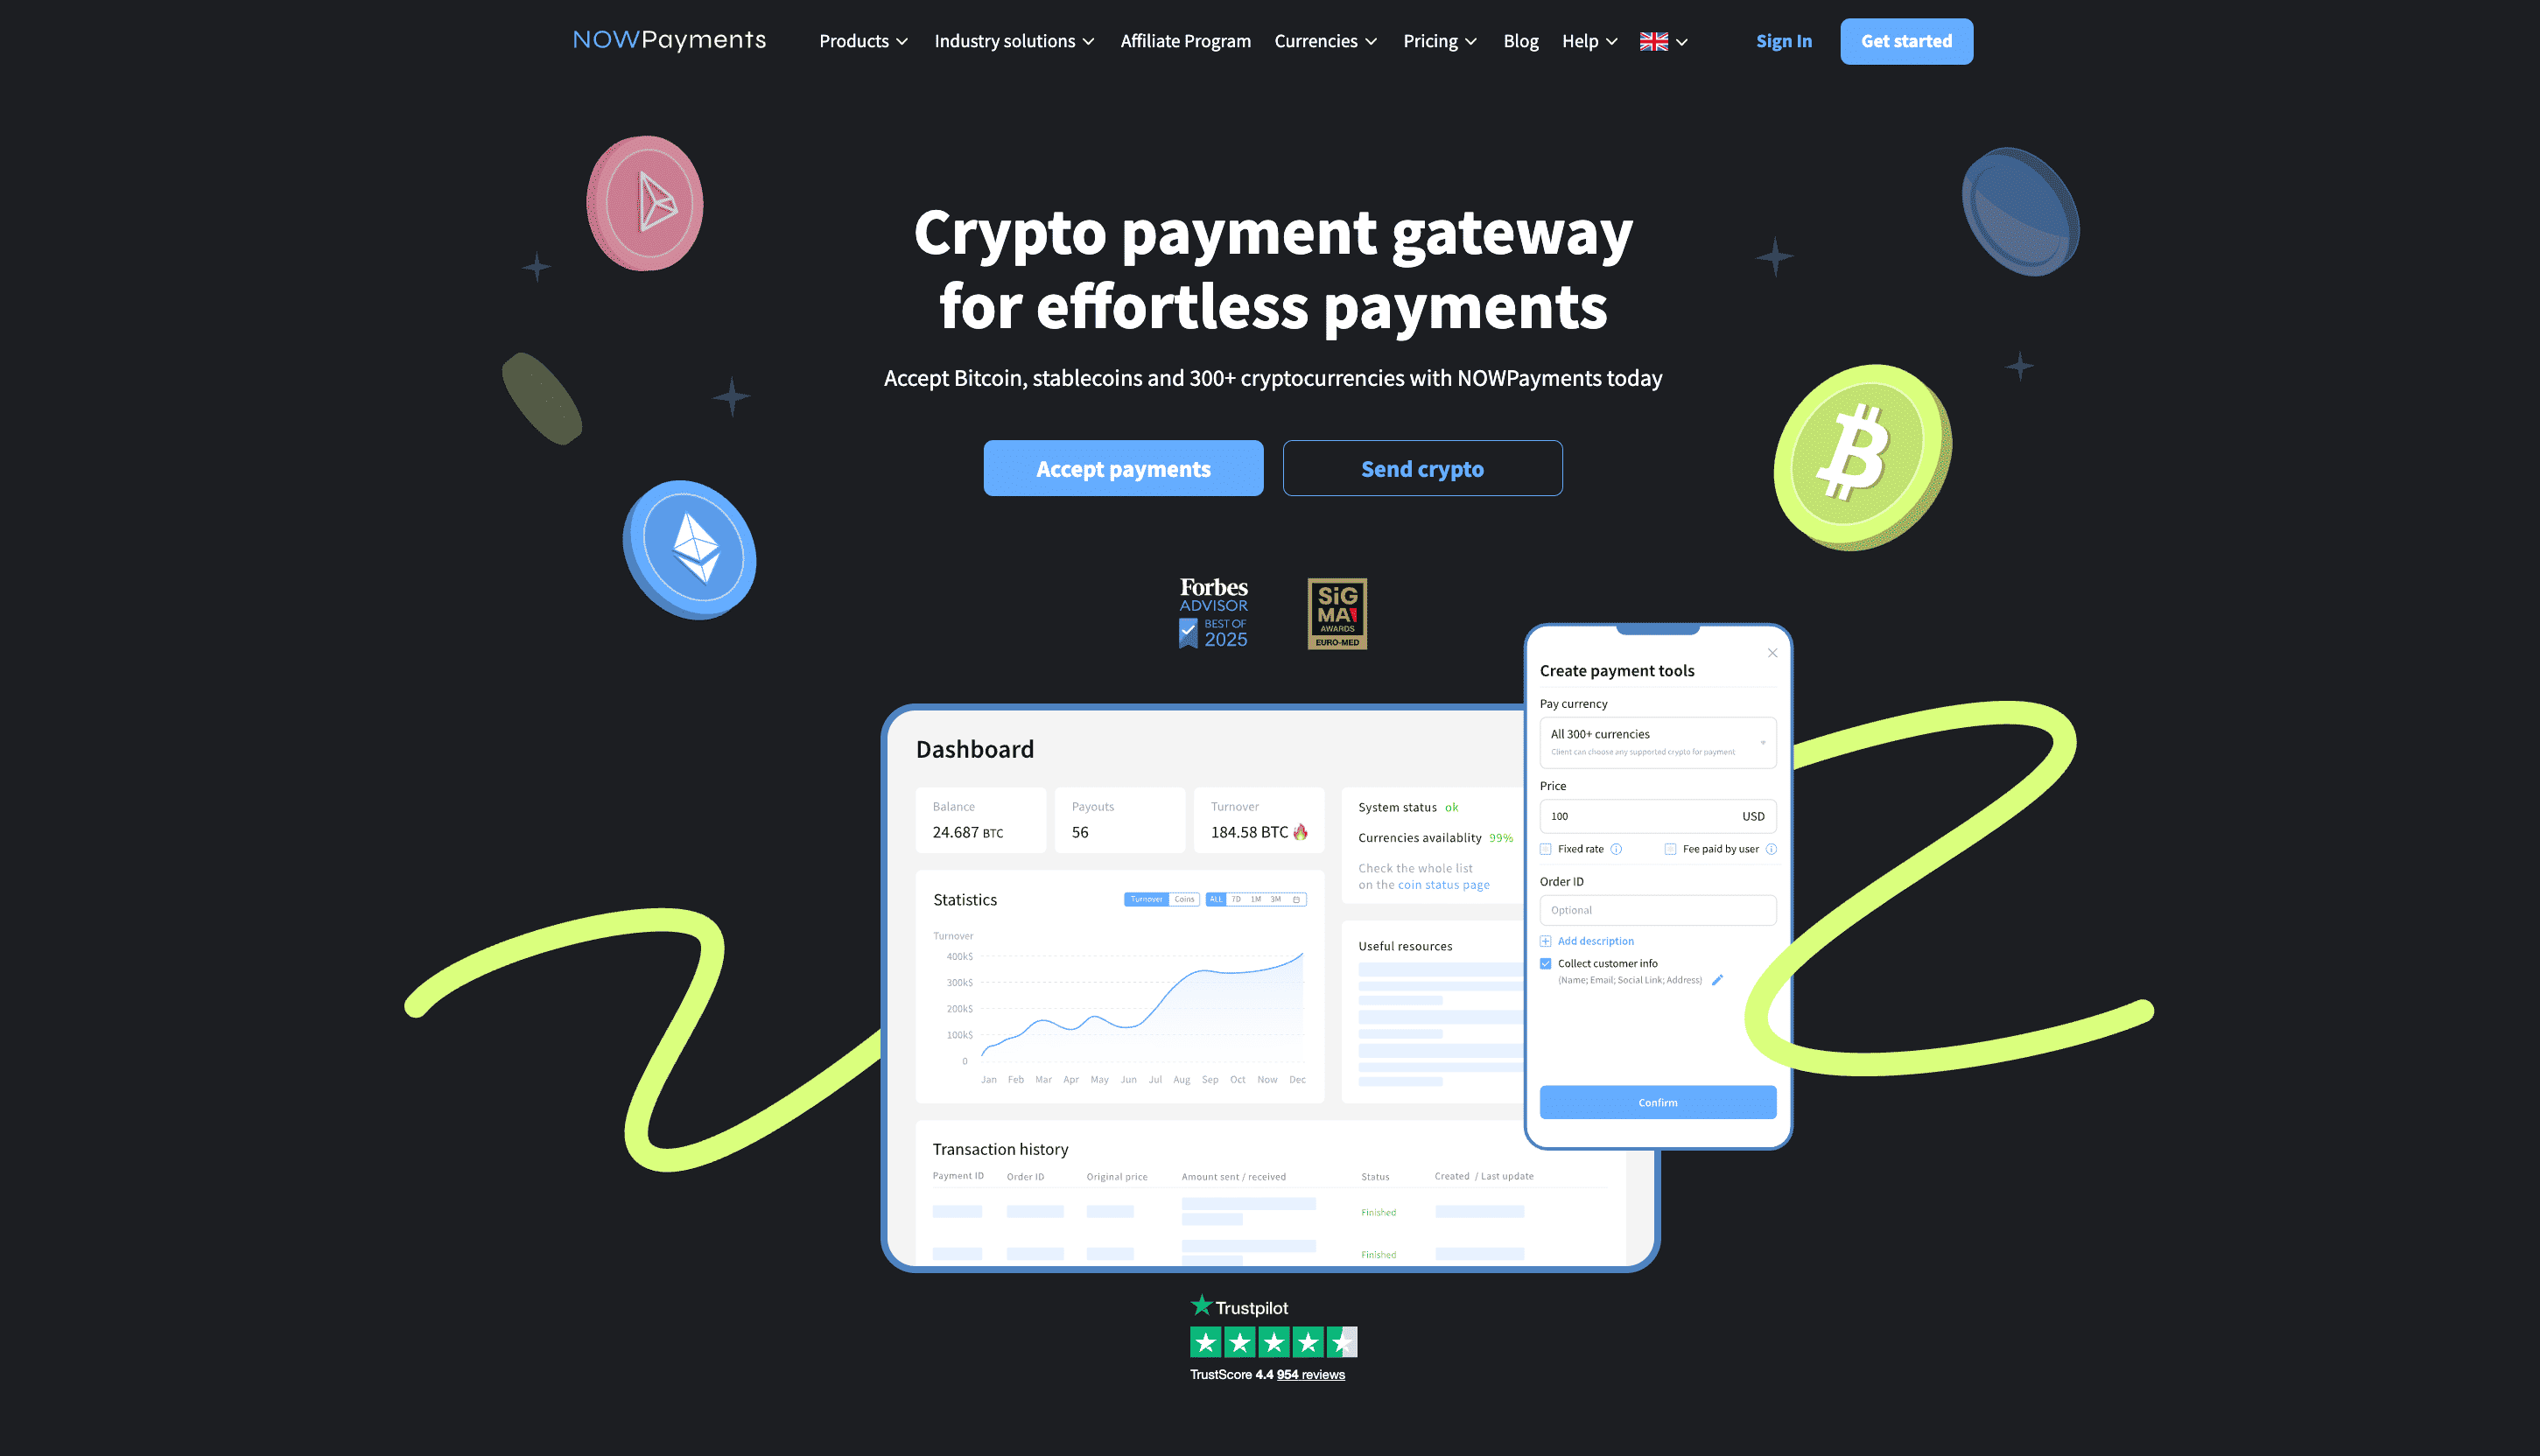
NOWPayments is a crypto payment gateway built as a full business ecosystem. It combines acceptance, mass payouts, conversions, custody wallets, and treasury workflows in one account, with operational support that covers integration, tax reporting questions, and account optimization. The platform is custodial by default, which means it handles wallet infrastructure, rate locking, confirmations, and outbound transfers internally. This structure fits merchants that want to accept crypto payments, automate payouts to suppliers or affiliates, and manage a stablecoin treasury without hiring a blockchain team.
Supported Payment Methods. NOWPayments supports 30+ stablecoins and 300+ digital assets across major blockchains. Merchants can accept the original asset, auto-convert incoming funds to a stablecoin, or route balances directly to mass payouts. Fiat on- and off-ramps run through licensed partners.
| Feature | NOWPayments |
| USDT Support | ✅ |
| USDC Support | ✅ |
| Stablecoins | 30+ |
| Altcoin Support | 300+ |
| Chains | BTC, ETH, TRON, BNB Smart Chain, Solana, Polygon + more |
| Fiat Support | Via partners (Guardarian, Banxa) |
| Mass Payouts | ✅ |
| Custody Payouts | ✅ |
| Email Payouts | ✅ |
Transaction Fees. NOWPayments charges from 1% for single-currency deposits and 1.5% for multi-currency deposits, with partner rates as low as 0.3%. Withdrawals carry a 0% service fee, and conversions cost 0.5%. Setup, integration, and dedicated support are free, which keeps the total cost of ownership low for merchants that move funds frequently.
| Fee Type | Rate |
| Mono-Currency Deposits | From 1%, down to 0.3% |
| Multi-Currency Deposits | 1.5% |
| Conversions | 0.5% |
| Payouts | 0% service fee |
| ChangeNOW Pro Payouts | $0 network fee |
| Setup & Support | $0 |
Business-Focused Features. NOWPayments processes 99% of deposits in under one minute, and mass transfers clear in an average of 1 to 3 minutes. Withdrawals to ecosystem wallets arrive in under one second through the email payout solution, while standard stablecoin payouts average 26 seconds on BNB Smart Chain and 94 seconds on Ethereum ERC-20. The platform provides API access, plugins for major e-commerce systems, and 24/7 support with custom account optimization.
| Feature Area | Key Capabilities |
| Revenue Infrastructure | Payments, payouts, conversions, custody |
| Treasury Automation | API, scheduled withdrawals, dashboard controls |
| Stablecoin Settlement | USDT, USDC, cross-border transfers |
| Enterprise Scale | High-volume processing, custom terms, 24/7 support |
| Payouts | Email payouts, under 1-second delivery |
What Makes NOWPayments Different:
- Business ecosystem NOWPayments covers acceptance, mass transfers, conversions, custody wallets, and subscriptions in one dashboard, with room to grow into affiliate and creator monetization.
- Zero-fee payouts. ChangeNOW Pro transfers carry a 0% service fee and $0 network fee, which is rare for high-volume processors.
- Speed without extra effort. Most deposits finish in under one minute, mass transfers clear in 1–3 minutes, and email payouts land in under a second, even for merchants without an in-house blockchain team.
Sources:
ABA PayWay
Best for: Card acceptance and KHQR in one checkout, with direct settlement to an ABA business account.
Skip it if: You want a published rate card, digital asset settlement, or a provider without a mandatory ABA Bank account.
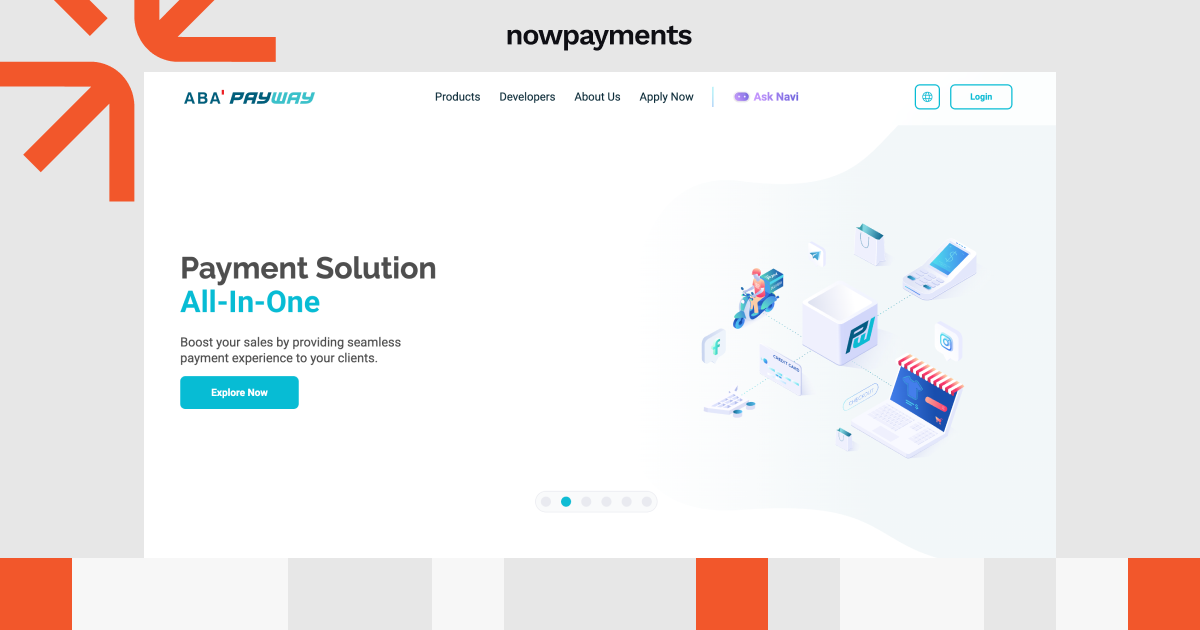
ABA PayWay is the merchant gateway of ABA Bank, run on payway.com.kh and positioned as the default checkout service for Cambodian e-commerce. The bank behind it leads the country in mobile banking with over 4 million app users, and the gateway is PCI DSS Level 1 certified with 3-D Secure 2.0. For businesses that sell online and want cards, local QR, and tourist wallets in one integration, it is the most widely documented payment solution in the market.
Supported Payment Methods. ABA PayWay accepts major international cards alongside local rails. The ABA Pay account-to-account QR confirms transfers in seconds, and KHQR extends acceptance to customers of every Bakong-member bank. Settlement lands directly in the merchant’s ABA business account in USD or KHR.
| Feature | ABA PayWay |
| Cards | Visa, Mastercard, UnionPay, JCB (Amex reported) |
| ABA Pay QR | ✅ |
| KHQR (Bakong) | ✅ |
| Google Pay | ✅ |
| Alipay | ✅ |
| WeChat Pay | ✅ |
| Currencies | USD, KHR |
Transaction Fees. ABA PayWay does not publish an official merchant rate card. Third-party integrators report card processing around 3.6–3.8% per transaction, with lower rates for ABA’s own cards, so merchants should treat any figure as indicative until ABA confirms it in writing. The monthly platform fee is officially zero.
| Fee Type | ABA PayWay |
| Card Processing | ~3.6–3.8% (third-party reports, not official) |
| Monthly Fee | $0 |
Business-Focused Features. ABA PayWay offers hosted checkout, payment links for social commerce, an invoicing tool, recurring card-on-file payments, and a split-payout API. ABA Pay QR confirmations arrive in seconds, while card settlement cycles are contract-specific and not publicly documented. The developer suite includes a sandbox, a WooCommerce plugin, and Shopify compatibility.
| Feature Area | Key Capabilities |
| Checkout | Hosted page, payment links, invoicing |
| Recurring Billing | Card-on-file auto-payments |
| Payouts | Split-payout API |
| Integration | REST API, sandbox, WooCommerce, Shopify |
What Makes ABA PayWay Different:
- Bank-direct settlement. Funds arrive in the merchant’s ABA account without an intermediary, which simplifies reconciliation for USD and KHR balances.
- E-commerce tooling depth. Payment links, invoicing, and subscriptions cover use cases from Instagram sellers to subscription businesses.
- Zero monthly fee. Officially published and verifiable on the provider’s site, unlike the processing rate.
Sources:
ACLEDA TOANCHET Pay
Best for: Merchants that want the country’s largest bank behind their checkout and the broadest cross-border QR coverage.
Skip it if: You run a small online store that needs a self-serve signup, published pricing, or quick API onboarding without a bank relationship.
ACLEDA TOANCHET Pay is the e-commerce gateway of ACLEDA Bank, Cambodia’s largest commercial bank by assets, deposits, and branch network. Launched in 2015 and operated under the bank’s TOANCHET Pay brand, it serves a merchant base that exceeded 555,000 QR and e-commerce outlets in 2024. For businesses that value institutional scale, a 4.4-million-user super app, and settlement into the country’s biggest banking network, this payment processor offers reach that smaller providers cannot match.
Supported Payment Methods. The gateway accepts Visa, Mastercard, JCB, and Diners Club cards, processed through Mastercard’s platform, alongside KHQR transfers in both USD and KHR. WeChat Pay QR serves Chinese visitors, and cross-border links cover PromptPay (Thailand), VietQR (Vietnam), SGQR (Singapore), JPQR (Japan), DuitNow (Malaysia), and India’s UPI, the latter reaching roughly 4.5 million Cambodian merchant outlets since June 2026.
| Feature | ACLEDA TOANCHET Pay |
| Visa / Mastercard | ✅ |
| JCB / Diners Club | ✅ |
| KHQR (Bakong) | ✅ |
| AC Super App | ✅ |
| WeChat Pay | ✅ |
| Cross-Border QR | 7 schemes (TH, VN, SG, JP, MY, LA, IN) |
| Settlement Currency | USD (cards auto-converted at network rates) |
Transaction Fees. ACLEDA quotes merchant pricing on request and publishes no rate card for the gateway. The only public datapoint comes from the online retailer SEAGM, which applies a 1.5% processing fee on ACLEDA checkout, a merchant-specific rate rather than the bank’s tariff. Businesses should budget only after receiving a written quote from a branch.
| Fee Type | ACLEDA TOANCHET Pay |
| Processing | Quote-based (1.5% seen at one large merchant) |
| KHQR Acceptance | Included with merchant onboarding |
Business-Focused Features. Integration options include a hosted checkout, host-to-host connections, app deeplinks, and payment links, with a sandbox and API documentation for developers. KHQR and Bakong transfers settle in seconds by design of the national rail, while card settlement cycles into the mandatory ACLEDA account are contract-specific. The accompanying SmartPay POS fleet exceeds 7,000 terminals for merchants that also sell in person.
| Feature Area | Key Capabilities |
| Integration | Hosted, H2H, deeplinks, payment links |
| POS Network | 7,052+ SmartPay terminals |
| Merchant Portal | Reports, refunds, voids, sub-users |
| Cross-Border | UPI, PromptPay, VietQR and 4 more |
What Makes ACLEDA TOANCHET Pay Different:
- Institutional scale. Cambodia’s largest bank, roughly US$10–12 billion in assets and 555,000+ merchant outlets, backs every transaction.
- Widest cross-border QR menu. Seven linked schemes, including India’s UPI, cover most visiting tourist populations.
- Full-service onboarding. Branches, a merchant portal, and POS hardware come from one provider.
Sources:
Wing Bank
Best for: SMEs that want free KHQR acceptance, an agent network for cash-in, and instant wallet settlement.
Skip it if: You need published merchant fees, international card acquiring for online checkout, or multi-currency settlement beyond USD and KHR.
Wing Bank runs the largest mobile-money footprint in Cambodia: over 10 million registered customers, 12,000+ agents, and 200,000+ SME merchants on its books. Founded in 2008 by ANZ and now a fully Cambodian-owned commercial bank under the Royal Group, it holds a full banking license from the National Bank of Cambodia since January 2021. For shops, restaurants, and social sellers, its merchant app plus free KHQR code is the fastest route from zero to accepting every bank transfer in the country.
Supported Payment Methods. WingPay merchant QR accepts transfers from Wing wallets and every Bakong-member bank through KHQR, plus Alipay and WeChat Pay for Chinese customers. EMV POS terminals handle Visa, Mastercard, and UnionPay cards with daily settlement, and cash-in or cash-out runs through 12,000+ Wing Cash Xpress agents across all provinces.
| Feature | Wing Bank |
| KHQR (Bakong) | ✅ Free for merchants |
| Wing Wallet / WingPay | ✅ |
| Visa / Mastercard / UnionPay | ✅ (POS) |
| Alipay | ✅ |
| WeChat Pay | ✅ |
| Agent Cash-In/Out | 12,000+ agents |
| Currencies | USD, KHR |
Transaction Fees. Wing advertises KHQR merchant acceptance as free of charge, which makes it the only provider in this comparison with a published zero-rate rail. Other merchant fees sit in an internal schedule referenced by the bank’s Customer Master Agreement and are disclosed during onboarding rather than online.
| Fee Type | Wing Bank |
| KHQR Acceptance | $0 (officially advertised) |
| POS / Other Processing | On request |
Business-Focused Features. WingPay merchant app generates KHQR codes, manages cashiers and outlets, and delivers transaction reports, with settlement advertised as instant and arriving in seconds after each confirmation. POS terminals settle daily. The OpenAPI Marketplace provides documented APIs and a sandbox for businesses building custom flows, and enterprise clients can run payroll and mass disbursements through the bank.
| Feature Area | Key Capabilities |
| Merchant App | KHQR generation, cashier management, reports |
| Settlement | Seconds to Wing account; daily on POS |
| Developer Access | OpenAPI Marketplace with sandbox |
| Enterprise | Payroll, disbursement, tax collection |
What Makes Wing Bank Different:
- Free KHQR acceptance. Merchants pay nothing to receive transfers from every bank and wallet in the country.
- Cash bridge. A 12,000-agent network connects digital balances to cash in provinces where banks are thin on the ground.
- Seconds-level settlement. Wallet receipts land in the merchant’s Wing account within seconds, with real-time Telegram notifications.
Sources:
Pi Pay
Best for: Wallet-first QR acceptance with Alipay and WeChat Pay reach for Chinese tourists.
Skip it if: You need published settlement terms, broad rural coverage, or deep online checkout tooling.
Pi Pay launched in July 2017 as one of Cambodia’s first e-wallets and became the country’s first Alipay partner in December 2017. Smart Axiata’s SmartLuy merged into the company in 2020, and Pi Pay PLC remains licensed by the National Bank of Cambodia. For tourism-facing retail, food service, and lifestyle businesses, its wallet discounts and Chinese wallet coverage still carry marketing weight.
Supported Payment Methods. Customers pay from the Pi Pay wallet in USD or KHR, and merchant QR codes also accept Alipay and WeChat Pay. Wallet top-ups run through bank transfers from ABA, Sathapana, Amret, and RHB, Pay&Go machines, and AMK cash-in points. Card acceptance historically ran through processing partners rather than Pi Pay itself, and 2026 industry reviews confirm KHQR interoperability, so wallet users can pay at any KHQR-enabled merchant.
| Feature | Pi Pay |
| Pi Pay Wallet | ✅ |
| Alipay | ✅ |
| WeChat Pay | ✅ |
| Bank Top-Ups | ABA, Sathapana, Amret, RHB, AMK |
| KHQR (Bakong) | ✅ |
| Cards | ⚠️ Via partners |
Transaction Fees. Pi Pay does not publish merchant fees, and rates are negotiated per business. Third-party directories describe consumer wallet use as free, with merchant pricing settled case by case during onboarding.
| Fee Type | Pi Pay |
| Merchant Processing | On request |
| Consumer Wallet | Free |
Business-Focused Features. Merchants get QR acceptance, POS terminals, and a dashboard for tracking transactions, plus PHP APIs and mobile SDKs for custom integration. Settlement terms are not published; businesses should expect a window in line with the local market norm of 1 to 3 business days and confirm it in the contract. In-app discounts of 5–50% at partner merchants give businesses a marketing channel alongside raw acceptance.
| Feature Area | Key Capabilities |
| Acceptance | Wallet QR, POS terminals |
| Marketing | In-app discounts 5–50%, loyalty |
| Integration | PHP API, iOS/Android SDKs |
| Settlement | Not published; 1–3 days typical |
What Makes Pi Pay Different:
- Early-mover wallet brand. One of the first Cambodian e-wallets, with brand recognition among local users built since 2017.
- Alipay first. The first local Alipay partner, giving it a long head start with Chinese visitor spending.
- Built-in promotion. Partner discounts and loyalty features double as a customer acquisition channel for merchants.
Sources:
How to Choose a Payment Gateway in Cambodia
Every business in Cambodia mixes customers, currencies, and sales channels differently when evaluating local processors. A street-level shop may live on KHQR alone, an online store may need cards plus payment links, and an exporter may want stablecoin settlement from overseas buyers. Match these expectations to the rails each provider supports.
Use the steps below to narrow down a gateway for Cambodian operations.
- Map your money flows. Identify counter QR sales, online checkout, subscriptions, supplier payouts, staff payroll, and refund handling.
- Confirm currency needs. Decide whether you settle in USD, KHR, or both, and check conversion terms before the first transaction.
- Choose your custody model. Decide whether you want settlement to a local bank account, a wallet balance, or a stablecoin treasury for buyers who pay with crypto.
- Compare total fees. Look at processing rates, conversion spreads, payout fees, and hardware costs, and get every quote in writing.
- Check settlement speed. Compare seconds-level QR settlement against contract-specific card cycles, and confirm the exact T+ terms.
- Evaluate payout needs. If you pay suppliers, affiliates, or staff in volume, verify batch limits, speeds, and fees.
- Test the customer experience. A clear checkout, a KHQR code at the counter, and familiar tourist wallets reduce abandonment.
Payment Gateway Fees Compared
Cost structures vary across providers, and most Cambodian banks price individually. Understanding the total cost of ownership, including processing fees, platform charges, and settlement timing, helps merchants choose the best payment gateway for their volume.
| Provider | Platform Fee | Processing Fee | $1,000 Transaction Cost Example |
| NOWPayments | $0 | 0.3–1% | ~3–10 |
| ABA PayWay | $0 monthly | ~3.6–3.8% reported, not official | ~36–38 |
| ACLEDA TOANCHET Pay | Custom | Quote-based | Custom |
| Wing Bank | $0 (KHQR free) | KHQR $0; cards on request | ~$0 on KHQR |
| Pi Pay | Custom | On request | Custom |
*Rates are based on publicly available pricing pages and third-party integrator reports. Cambodian banks do not publish official merchant rate cards. Treat all local figures as indicative and confirm directly with each provider.
Total Cost Analysis
NOWPayments: From 1% for mono-currency deposits and 1.5% for multi-currency deposits, with rates from 0.3% for eligible partners. Payouts carry a 0% service fee, and ChangeNOW payouts also have no network fees.
ABA PayWay: Zero monthly platform fee is official. Processing reportedly runs ~3.6–3.8% per card transaction, which adds up quickly on volume, so negotiate before committing.
ACLEDA TOANCHET Pay: Quote-based pricing scales with the merchant’s size and relationship with the bank. One large online retailer passes a 1.5% processing fee to its customers, but that is a merchant-side rate, not the bank’s tariff.
Wing Bank: KHQR acceptance is free, making it the cheapest option for pure QR businesses. Card and POS pricing is disclosed during onboarding.
Pi Pay: Merchant fees are negotiated individually, so cost depends on bargaining position and volume. Smaller merchants have little visibility before talking to sales.
Crypto-First vs. Fiat-First Gateways
Payment providers for Cambodian businesses fall into two broad categories. Your choice depends on whether your revenue comes mainly from local customers on bank rails or from international buyers on digital-asset networks.
Blockchain-based gateways settle on crypto rails, enabling near-instant cross-border transfers and 24/7 operation. Stablecoins reduce volatility while keeping settlement fast. These gateways require stronger digital-asset accounting, tax tracking, and attention to network fees.
Crypto-first (blockchain and stablecoin rails):
- NOWPayments
Fiat-first (local bank, card, and QR rails):
- ABA PayWay
- ACLEDA TOANCHET Pay
- Wing Bank
- Pi Pay
Fiat-first gateways connect to Cambodian bank accounts, cards, KHQR, and tourist wallets. They offer familiar user experiences and straightforward USD and KHR accounting. Cross-border payouts, however, run through correspondent banking and can take days with meaningful FX markups.
When to Choose Each Payment Gateway in Cambodia: Decision Framework
Match a provider to your customer base, volume, currency needs, and technical resources, from a bank-backed gateway to a crypto payment processor.
Choose NOWPayments if you:
- Need a complete crypto business ecosystem covering deposits, conversions, custody, and treasury workflows.
- Serve international buyers and want mass payouts with no service fee.
- Operate across borders and need 24/7 support, stablecoin settlement, and API-driven treasury workflows.
Choose ABA PayWay if you:
- Sell online to Cambodian cardholders and want KHQR in the same checkout.
- Already bank with ABA or can open a business account there.
- Need plugins for WooCommerce or Shopify rather than raw API work.
Choose ACLEDA TOANCHET Pay if you:
- Want the largest bank network in the country behind your settlements.
- Serve tourists from India, Thailand, Vietnam, or China via cross-border QR.
- Need POS terminals alongside your online checkout.
Choose Wing Bank if you:
- Want free KHQR acceptance and seconds-level settlement to a wallet balance.
- Operate where cash still matters and need 12,000+ agents for cash-in.
- Run payroll or disbursements for staff and suppliers.
Choose Pi Pay if you:
- Target Chinese tourists with Alipay and WeChat Pay at the counter.
- Want wallet-based marketing and loyalty features alongside acceptance.
- Can work with negotiated pricing and unpublished settlement terms.